FAQ on E-invoicing under New GST Returns

GST Council introduced e-Invoicing from 1st January, 2020 on a voluntary basis, for reporting of business to business (B2B) invoices. The GST Council had approved the standard to be used for the e-Invoice in its 37th meeting that was held on the 20th of September, 2019 in Goa. Below are some FAQs on the e-Invoicing system under GST.

What is e-invoicing?

Electronic invoicing or E-invoicing is the new system through which business to business (B2B) transactions are authenticated electronically by GSTN for further use on the common GSTN portal. In simpler words, it is an invoice generated using a standardised format, where the electronic data of the invoice can be shared with others, thus ensuring interoperability of data.

Issue of e-invoices by the taxpayers registered under GST having a turnover above Rs 500 crores has been notified on 13th Dec 2019.

How does e-invoicing model work?

Today, a transaction between the supplier and recipient is done directly without the government having any proof of the exchange. Under the e-Invoicing model, businesses will continue to generate invoices on their respective ERPs just the way it was being done in the past. The only difference is that, the standard, schema and format for the generation of invoices will be specified, to ensure a level of standardisation and the machine-readability of these invoices.

With e-invoicing, the moment an invoice is made, it will be uploaded to GSTN portal where pre-validation will be done, and a unique number called IRN (Invoice Reference Number) will be issued which will then be digitally signed. Once IRN is issued, it will then generate a QR code, containing vital parameters of the e-Invoice. This will be returned to the same to the taxpayer who generated the document in the first place. The IRP will also send the signed e-Invoice to the recipient of the document, on the email ID provided in the e-Invoice.

What are the types of documents that are to be reported into the IRP?

The following documents will be covered under e-Invoicing for now:

  • Invoices by the Supplier
  • Credit Notes by the Supplier
  • Debit Notes by the Recipient
  • Any other document as required by law to be reported by the creator of the document

What is the workflow of e-invoice?

Step 1 – Generation of e-invoice:

The taxpayer will continue to generate invoices in the normal course of business. However, the reporting of these invoices electronically has criteria. It needs to be done as per the e-invoice schema along with mandatory parameters. The mandatory fields of an invoice for the supply of goods are listed below:

  • Invoice type
  • Code for invoice type
  • Invoice Number
  • Invoice Date
  • Supplier details like Name, GSTIN of Supplier, Supplier address (including place, pin code, state)
  • Details of the buyer such as name, GSTIN, state code, address, place, pin code, payee name, account number, payment mode and IFSC code
  • Dispatch details
  • Invoice item being dispatched
  • Total tax amount, paid amount and payment due
  • Tax scheme (whether GST, Excise Custom, VAT)
  • ‘Shipping To’ details like Name, GSTIN, address, pin code, state, supply type, transaction mode (whether regular, ‘bill to’ or ‘ship to’)
  • Details of goods like Sl. no., quantity, rate, assessable value, GST rate, amount of CGST/SGST/IGST, total invoice value, batch number/name

The seller has to ensure that his accounting/billing software is capable of generating a JSON of the final invoice. The seller can create a JSON following the e-invoice schema and mandatory parameters by using the following modes:

  • Accounting and billing system that offers this service
  • Utility to interact with either accounting/billing system, ERP, excel/word document or a mobile app
  • Offline Tool to generate e-invoice by keying-in invoice data

Step 2 – Generation of unique IRN:

The supplier has the option to generate ‘hash’ based on specific parameters usually three of them such as Supplier’s GSTIN, Supplier’s invoice number, Financial Year (YYYY-YY). The prescribed algorithm, such as SHA256 must be used for the hash generation. If the hash is validated, it would later become the Invoice Reference Number (IRN) of the e-invoice.

Step 3 – Uploading the JSON:

The following modes may be used to upload the JSON of the final invoice:

  • Directly on the IRP
  • Through GST Suvidha Provider (GSP)
  • Third-party provided apps (including through API)
  • The supplier can also upload the hash along with the JSON onto the IRP, if generated by him

Step 4 – Hash generation/validation:

Hash will have to be generated by the IRP in respect of the invoices uploaded without the hash. In such a case, the hash generated by the IRP would become the IRN. Where the supplier has also uploaded hash, a de-duplication check will be performed. It is done by validating the hash/IRN against the Central Registry of GST System to ensure that the IRN is unique. Once validated, the hash/IRN is stored in the Central Registry. IRP will then generate a QR Code and digitally sign the invoice and make it available to the supplier. The IRP also sends the e-invoice via e-mail mentioned on the invoice to the buyer and seller.
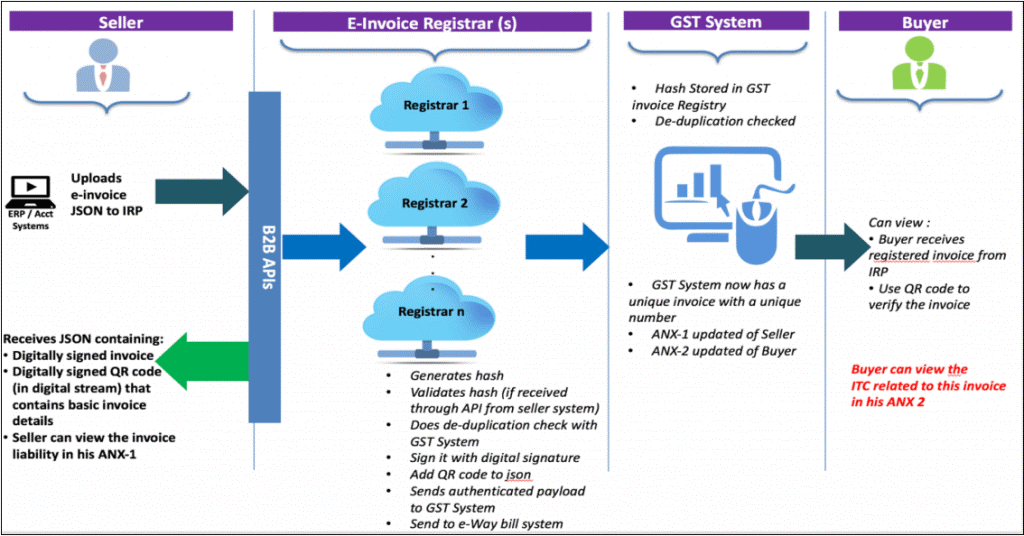
Source: last FAQ doc released by GSTN

How will the system of e-invoicing be integrated with GST Returns?

An e-Invoice will be uploaded into the relevant GST return only once it has been validated and registered by the invoice registration system. After the validation has been done, it will be visible to the recipient for viewing and taking action (in the new return system).

The main aim of the tax department is to enable the pre-population of GST returns, which will reduce reconciliation-related problems. Once e-Invoicing has been implemented, the data in the invoices can be pre-populated into the relevant tables of the tax returns without the need for fresh data entry.

What data will be included in an e-invoice?

As per the draft format generated by the GSTN, an e-Invoice will contain the following parts-

  • E-invoice schema: This part will consist of the technical field name and the description of each field. It will also specify if a field is mandatory or not, and has a few sample values along with explanatory notes
  • Masters: Masters will specify the set of inputs for certain fields, that are pre-defined by GSTN itself. It includes fields like UQC, State Code, invoice type, supply type, etc
  • e-Invoice template: The template is as per the GST rules and enables the reader to correlate the terms used in other sheets. The mandatory fields are marked in green and optional fields are marked in yellow

What are the benefits of e-invoicing?

  • One-time reporting of B2B invoices while generation, which reduces reporting in multiple formats
  • Sales and Purchase Registers can be generated from this data, and GST returns can be kept ready for filing under the new return system
  • E-way bills can also be generated using e-Invoice data
  • There is minimal need for data reconciliation between the books and GST returns filed
  • Real-time tracking of invoices prepared by a supplier can be enabled, along with the faster availability of input tax credit. It will also reduce input tax credit verification issues
  • Automation of the tax-filing process
  • Reduction in the number of frauds as the tax authorities will also have access to data in real-time
  • Elimination of fake GST invoices getting generated
Difference between Old Vs New GST Return System

Introduction

The Indian government aimed at introducing GST to streamline the taxation policies even further. Under GST scheme, businesses followed the rule of ‘One Nation, One Tax’ which helped several taxpayers stay compliant seamlessly. However, several entrepreneurs found GST a bit complicated with numerous forms which are to be filed. Thus, to make the taxation system more simplified, the government announced the launch of GST 2.0 aka New Return Filing. The objective of the New Simplified GST Returns is to completely knock off the tax evasion pan India so that the transparency and equality can be attained under the indirect tax mechanism.

Let’s look at how different GST 2.0 is from the old return filing mechanism and how it will benefit the taxpayers.

Under the old return filing system

GSTR-1 return should be filed for reporting outward supplies and declaring tax liability on the same. Input Tax Credit (ITC) on imports has to be claimed in GSTR-3B under eligible ITC.

The taxpayer has to file monthly GSTR-1 if his annual turnover is more than Rs.1.5 crore. Otherwise, the taxpayer can file a quarterly GSTR-1.
This return includes/developers on a bill of entry

S. no Particulars
1 Supplies made to registered persons other than reverse charge mechanism (RCM) supplies and supplies through e-commerce operator
2 Supplies made under reverse charge mechanism
3 Supplies made through e-commerce operator
4 Interstate supplies to unregistered persons where invoice value is more than Rs.2.5 lakh
5 Zero rated supplies and deemed exports
6 Nil rated, exempted and non-GST outward supplies
7 Amendments to taxable outward supply
8 Advances received/adjusted during the tax period
9 HSN-wise summary of outward supplies
10 Documents issued during the tax period

Under the new return filing system

GST ANX-1 should be filed for reporting sales and declaring tax liability on the sales. Imports are also to be reported in GST ANX-1 and ITC on imports will be auto-populated in GST RET-1.
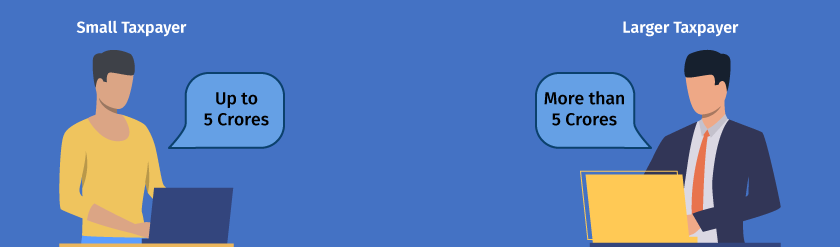
In the new return system, taxpayers are categorised into large taxpayer (whose annual turnover is more than Rs.5 crore) and the small taxpayer (whose annual turnover is up to Rs.5 crore). A large taxpayer has to file monthly GST ANX-1, whereas the small taxpayer can file his GST ANX-1 monthly or quarterly at his option.

This return includes

S No Particulars
1 Supplies made to consumers and unregistered persons
2 Supplies made to registered persons (Other than RCM supplies)
3 Exports with/without payment of tax
4 Supplies to SEZ units/developers with/ without payment of tax
5 Deemed exports
6 Inward supplies attracting reverse charge
7 Import of goods/services
8 Import of goods from SEZ units/developers on a bill of entry
9 Missing invoices which are to be uploaded by recipients
10 Details of the supplies made through e-commerce operators
11 Amendments to various supplies

Comparison – old vs new GST return system

The form GST ANX-1 under the new return system is similar to GSTR-1 under the old return system. There are some changes under the new return system when compared to old return system. Some of them are

  • Reporting of Supplies Under RCM

In the current filing system, invoice details can be reported while filing GSTR 1 form but can be viewed afterwards in GSTR-2A. In the new filing system, filing and viewing go simultaneously so that instant action can be taken on that.

  • HSN Summary Reporting

Under the old return system, the HSN code summary needs to be reported separately. But in the new return system, the supplier has to report the HSN codes at the invoice level (based on his turnover). In this way, the taxpayer will get the HSN data via his GST ANX-2 wherever the supplier was required to declare HSN.

  • Reporting of Imports

Under the old return filing system, ITC on imports alone has to be reported in GSTR-3B. However, under the new return filing system, the taxpayer has to report imports of goods and services in GST ANX-1.

  • Tax Payment

In the current system, Full Tax liability must be paid for a tax period while filing monthly return GSTR-3B. In the new system, complete Tax liability must be paid for a tax period in monthly PMT-08, regardless of monthly or quarterly filing of GST returns.

  • Reporting of Documents Issued

Under the new return system, there is no requirement for reporting of documents (along with serial numbers) like invoices, debit/ credit notes, receipt/ payment/ refund vouchers, delivery challans which were issued during the tax period.

GST Return Filing Date for March-May Extended till June Amid Corona Virus

GST_Return_Filling_Date

The government on March 24 announced extension of the last date for filing GSTR-3B for Goods and Services Tax (GST) for March, April and May to June 30, amid the Corona Virus chaos. “Others can file returns due in March, April and May 2020 by last week of June 2020 but the same would attract a reduced rate of interest at 9 percent per annum from 15 days after due date (current interest rate is 18 % per annum),” she said.

Bigger companies, the FM said, would have to pay only interest but no late fee or penalty will be imposed. “No late fee and penalty to be charged, if complied with before or till 30th June 2020,” she said.

In a press conference, Sitharaman announced some crucial measures to fight the economic fallout of Covid-19 pandemic. The government also extended the date till the last week of June, for opting for composition scheme. “Further, the last date for making payments for the quarter ending 31st March, 2020 and filing of return for 2019-20 by the composition dealers will be extended till the last week of June, 2020,” the FM said.

The date for filing GST annual returns of 2018-19, which was due on March 31, has been extended till the last week of June. “Due date for issue of notice, notification, approval order, sanction order, filing of appeal, furnishing of return, statements, applications, reports, any other documents, time limit for any compliance under the GST laws where the time limit is expiring between 20th March 2020 to 29th June 2020 shall be extended to 30th June 2020,” the government said.

Sitharaman also extended the deadline for filing FY19 income tax (I-T) returns till June 30. ATM charges have been scrapped till June 30.

FORM RET 1 – Quarterly GST Return

In the 31st meeting of GST Council, it was recommended to introduce and implement a new GST return system. One of the key aspects of the new GST return system is the introduction of different types of return forms considering the business profile. Quarterly return form RET-1 is one such return type designed for small taxpayers.

In this blog, let us understand the applicability, return filing period and format of quarterly return form RET-1

What is quarterly return form RET-1?

Quarterly Return form RET-1 is a return type for small taxpayers whose aggregate turnover in the financial year does not exceed 5 Crores and their outward supplies consist of B2B B2C and all other types supplies such as exports, SEZ etc.

To put it in simple words, businesses opting quarterly return form RET-1 will be allowed to make all types of outward supplies such as supplies to end consumers, unregistered business, registered business, exports, SEZ etc.

Except for the periodicity of filing return, the form type, format and details required to be furnished are similar to monthly returns.

Periodicity of filing quarterly return form RET-1

The periodicity of filing quarterly return form RET-1 is similar to the Sahaj and Sugam. You need file the returns quarterly with a monthly payment of tax on a self-assessed basis. The due date to file a quarterly return in Form RET-1 is 25th of the subsequent month following the quarter-end.

The due date for filing Sugam GST returns is given below

Quarterly Return Form RET-1
Quarters Due Data
April -June 25th July
July – September 25th October
October- December 25th January
January-March 25th April

Due date for payment of tax

Though the return filing periodicity is quarterly, businesses opting quarterly RET-1 are required to make the monthly payment.

The tax payment is on the self-assessed basis and the payment declaration challan known as Form GST PMT -08 should be used to remit the payment. The due date to remit the monthly payment is 20th of the subsequent month.

Types of supplies allowed under quarterly GST Return Form RET-1

Business opting quarterly return Form RET-1 will be allowed to make all types of supplies as mentioned in the below table.

Type of Outward Supplies Allowed (Yes) / Disallowed (No)
B2B transactions Yes
B2C transactions Yes
Exports Yes
SEZ units/developers Yes
Deemed Exports Yes
Outward Supply to e-Commerce Operators Yes
Nil Rated, Exempted or Non – GST Yes
Inward supplies attracting RCM Yes
Import of goods/services Yes
Import of Goods from SEZ Yes


Difference between Sahaj, Sugam and quarterly return form RET-1

All these returns are quarterly and designed for small taxpayers. The first difference, the obvious one is that each of these returns differs basis nature of supplies it supports. Sahaj supports only B2C supplies, Sugam supports B2C as well as B2B supplies and quarterly return form RET-1 support all types of supplies.

Second, the most important one, the facility of availing ITC on the missing invoice (invoices not uploaded by the supplier) and reporting of such bills is allowed for businesses opting monthly return and quarterly return in form RET-1. In other words, businesses who have opted Sahaj return and Sugam return will not be allowed avail ITC on the missing invoice.

Quarterly return form RET-1 return filing process

The quarterly return form RET-1 consist of one main return, to be filed on a quarterly basis supported by two main annexures. Form GST RET-1 is the return form to be used to file Sugam returns supported by the annexures.

The details of return forms and annexures to be used for filling Sugam return is given below.

Form Description Action
Form GST ANX- I Form GST ANX-1 is an annexure of outward supplies and inward supplies attracting reverse charge. You need to upload details of outward supplies along with purchases attracting reverse charge in FORM GST ANX – 1
Form GST ANX – II It’s an annexure containing details of auto-drafted inward supplies.


Form GST ANX-II is an auto-populated annexure containing the details document uploaded by your supplier on a real-time basis.

Here you can either accept, modify or reject the invoice uploaded by your counterpart (seller) for confirming the ITC.

Form RET-1 Form RET-1 is a quarterly return applicable for business opting Sugam returns (Up to 5 Crores) Business need to file the monthly return by 25th of the subsequent month following the quarter-end

Sugam GST Returns – Form GST RET-3

The new GST return framework has introduced a set of return forms specially designed for small taxpayers. Among the new returns available, Sugam return form is once such GST return aims to simplify the GST complexities.

In this blog, let us discuss and understand Sugam returns, return filing periodicity, tax payment, format and filing process.

What is Sugam GST returns?

Sugam is a new GST return for small taxpayers whose aggregate turnover in the financial year does not exceed 5 Crores and their outward supplies consist of B2B as well as B2C. Businesses opting Sugam GST returns will be allowed to make outward supplies to end consumers, unregistered business and business registered under GST.

Applicability of Sugam return

To opt Sugam return under GST, you need to satisfy the below two conditions.

  • The aggregate turnover in the previous financial years is up to 5 crores
  • You are engaged in making B2B supplies (Unregistered Business and end consumers) and B2B supplies (supplies to business registered under GST)

Periodicity of filing Sugam return

The periodicity of Sugam return filing is on a quarterly basis with a monthly payment of tax. For businesses opting Sugam GST return, the due date to file a quarterly return is 25th of the subsequent month following the quarter-end.

The due date for filing Sugam GST returns is given below

Due Date to File Sugam GST Return
Filing Period Due Data
April -June 25th July
July – September 25th October
October- December 25th January
January-March 25th April

Due date for payment of tax

Though the return filing periodicity is quarterly, businesses opting Sugam return are required to make the monthly payment.

The tax payment is on the self-assessed basis and the payment declaration challan known as Form GST PMT -08 should be used to remit the payment. The due date to remit the monthly payment is 20th of the subsequent month.

Like Sahaj return, the self-assessed payment is required only for 1st and 2nd month of the and for 3rd month, payment with all adjustments should be made along with the returns.

Let’s understand with an example.

For April to June quarter, the taxpayer needs to remit the tax of April by 20th May and May’s tax by 20th June. For June, you need to pay tax along with first 2 months adjustment (if any) with main Sugam returns.

Difference between Sahaj and Sugam GST returns

While both the returns are quarterly and applicable for small taxpayers, basis the supplies nature it supports, these 2 differs. Sahaj as a small taxpayer return supports only B2C supplies whereas Sugam supports B2C as well as B2B supplies.

In other words, Sahaj return is suitable for businesses who are engaged in making only B2C outward supplies. On the other hand, Sugam is suitable for a business who make both B2C as well as B2B supplies.

Types of supplies allowed under Sugam returns

The following table gives the list of supplies allowed and disallowed under Sugam GST returns.

Type of Outward Supplies Allowed (Yes) / Disallowed (No)
B2B transactions Yes
B2C transactions Yes
Exports No
SEZ units/developers No
Deemed Exports No
Outward Supply to e-Commerce Operators No
Nil Rated, Exempted or Non – GST Yes
Inward supplies attracting RCM Yes
Import of goods/services No
Import of Goods from SEZ No

Sugam return filing process

The Sugam GST returns consist of one main return, to be filed on a quarterly basis supported by two main annexures. Form GST RET-3 is the return form to be used to file Sugam returns supported by the annexures.

The details of return forms and annexures to be used for filling Sugam return is given below.

Form Description Action
Form GST ANX- I Form GST ANX-1 is an annexure of outward supplies and inward supplies attracting reverse charge. You need to upload details of outward supplies along with purchases attracting reverse charge in FORM GST ANX – 1
Form GST ANX – II It’s an annexure containing details of auto-drafted inward supplies.


Form GST ANX-II is an auto-populated annexure containing the details document uploaded by your supplier on a real-time basis.

Here you can either accept, modify or reject the invoice uploaded by your counterpart (seller) for confirming the ITC.

Form RET-3 Form RET-3 is a quarterly return applicable for business opting Sugam returns (Up to 5 Crores) Business need to file the monthly return by 25th of the subsequent month following the quarter-end


The key point which businesses should take note is that the option to avail input tax credit on the missing invoices (invoices not uploaded by the supplier) is not available in Sugam returns. This implies that businesses will be allowed to avail the ITC to the extent of the invoices auto-populated in Form GST ANX-II.

However, the option to claim ITC on a provisional basis on the missing invoice is available for taxpayers opting monthly return and quarterly normal return using Form GST RET-1.

Format of Sugam returns – Form GST RET – 03

The Sugam form RET – 03 contains the details of supplies (both inward and outward) declared through Form GST ANX – 1 and GST ANX – 2. This is the main return form which auto-populates the information of supplies from the first two annexure forms. The supplier (taxpayer) needs to complete the remaining details and calculate their tax liability.

To summarize the Sugam return format (Form GST RET-3), it contains the summary level details of outward supplies, inward supplies and adjustments related to it. The Sugam return format consists of the following details:

  • Outward supplies
  • Inward supplies attracting reverse charge
  • Debit/credit notes
  • Advanced received
  • Total tax liability
  • Inward supplies for claiming ITC
  • Net ITC available
  • Amount of TDS/TCS credit received (Transition / Switchover)
  • Interest and late fee (if any) and
  • Final payable tax along with details of tax payment and
  • Refund claimed from the ledger.

Sahaj GST Returns – Form GST RET-2

By Introducing different return forms for different types of business, the new GST return system aims to simplify the filing process for business registered under GST. Sahaj GST return is one such form among the several types of new GST returns to be introduced.

In this blog, let us understand all about the Sahaj GST returns right from its applicability, periodicity of return filing, payment of tax and return filing process.

What is Sahaj return in GST?

Sahaj is a type of GST returns for small taxpayers whose aggregate turnover in the financial year does not exceed 5 Crores and their outward supplies are of B2C nature i.e. outward supplies are made to end consumers and unregistered business.

Applicability of Sahaj return

The criteria to decide on the applicability of the return depends on the aggregate turnover and types of outward supplies you make.

  • The aggregate turnover in the previous financial years is up to 5 crores
  • You are engaged in making only B2B supplies (Unregistered Business and end consumers)

If you satisfy the above two conditions, you will have an option to file Sahaj GST returns.

Periodicity of filing Sahaj return

The periodicity of Sahaj return filing is on a quarterly basis. However, the payment of tax should be made on a monthly basis.

For businesses opting Sahaj GST return, the due date to file a quarterly return is 25th of the subsequent month following the quarter-end. Following are due date for filing Sahaj returns.

Due Date to File Sahaj GST Return
Quarters Due Data
April -June 25th July
July – September 25th October
October- December 25th January
January-March 25th April

Due date for payment of tax

Taxpayers opting Sahaj return are required to make the monthly payment though the return filing periodicity is quarterly. The payment of tax is on the self-assessed basis and should be made through a payment declaration form known as Form GST PMT-08. The due date for monthly payment of tax for Sahaj return is 20th of succeeding month.

The self-assessed payment is required only for 1st and 2nd month of the quarter and for 3rd month, payment along with all adjustments should be made along with the returns.

Sahaj return filing process

The Sahaj GST return consist of one main return, to be filed on a quarterly basis supported by two main annexures. Form GST RET-2 is the return form to be used to file Sahaj returns supported by the annexures.

The details of return forms and annexures to be used for filling Sahaj return is given below.

Form Description Action
Form GST ANX- I Form GST ANX-1 is an annexure of outward supplies and inward supplies attracting reverse charge. You need to upload details of outward supplies along with purchases attracting reverse charge in FORM GST ANX – 1
Form GST ANX – II It’s an annexure containing details of auto-drafted inward supplies.


Form GST ANX-II is an auto-populated annexure containing the details document uploaded by your supplier on a real-time basis.

Here you can either accept, modify or reject the invoice uploaded by your counterpart (seller) for confirming the ITC.

Form RET-2 Form RET-02 is a quarterly return applicable for business opting Sahaj returns (Up to 5 Crores) Business need to file the monthly return by 25th of the subsequent month following the quarter-end

Types of New GST Return Forms and Annexures

In a bid to simplify the GST compliance, the GST Council has proposed the new GST returns expected to be introduced from 1st October,2020.  Considering the diversity of businesses operating in the country, different returns forms supported with annexure are proposed as a part new return framework.

while the idea of different returns for different business aims at simplifying the GST compliance, businesses are recommended to carefully asses the business profile, their vendors, supply type etc. and accordingly choose the one which suits the most.

Having said there are different returns, the immediate question which comes to mind is what are the returns that are available on the GST shelf? Which return should I shop on the GST portal?

Let’s understand the different returns forms and annexures introduced in the new GST returns.

Return forms and Annexure in new GST Returns

Form Description Action
Form GST ANX- I Form GST ANX-1 is an annexure of outward supplies and inward supplies attracting reverse charge. You need to upload details of outward supplies along with purchases attracting reverse charge in FORM GST ANX – 1
Form GST ANX – II It’s an annexure containing details of auto-drafted inward supplies.


Form GST ANX-II is an auto-populated annexure containing the details of document uploaded by your supplier on a real-time basis.

Here you can either accept, modify or reject the invoice uploaded by your counterpart (seller) for confirming the ITC.

Form RET-1 (Monthly) Form RET-1 is a monthly return to be filed by the businesses having aggregate turnover over more than 5 Crores in a financial year. Business needs to file the monthly return by 20th of the subsequent month.
Form RET-2 Form RET-2 is a quarterly return applicable for business opting Sahaj returns (Up to 5 Crores) Business need to file the monthly return by 25th of the subsequent month following the quarter-end
Form RET-03 Form RET-02 is a quarterly return applicable for business opting Sugam returns (up to 5 Crores) Business need to file the monthly return by 25th of the subsequent month following the quarter-end
Form RET-1(Quarterly) This is similar to monthly return but applicable for business having aggregate turnover up to 5 crores. Business need to file the monthly return by 25th of the subsequent month following the quarter-end

As detailed in the above table, the main return will be supported by the annexures. Every return is supported by two annexures, one for reporting the outward supplies (liability) and the other one for inward supplies (ITC).

Among the main returns, you need to choose and file only one return which is suitable for your business profile.  Choosing the right GST return is key for simplification and assessing your business profile inline with new return types is must. This because each return form has its own implication on the Input tax credit.

Highlights of New GST Returns

The new GST returns proposed to be introduced on 1st October,2020, aims to drastically reduce the complexities attached to GST compliance in the current day. In order to allow businesses to get used to new returns, a trail functionality has been enabled on the GST common portal.

The prototype of new GST returns will enable the businesses to experience and learn the new functionality before it goes live. Before you get your hands into the prototype of new GST returns, it is recommended to know few key aspects of new GST returns.

Here are the key highlights of all-new simplified GST return which will come into effect from 1st April, 2020.

Classification of Taxpayers

Classification of Taxpayers under new gst

Under the new GST return framework, the taxpayers are classified into small Taxpayers and large taxpayers. Small taxpayers are those having annual turnover up to 5Cr in previous financial year and taxpayers having a turnover of more than 5 Cr in a previous financial year are treated as large taxpayers.

This change will widen the small taxpayer’s bracket eligible for quarterly returns from the existing threshold of 1.5 Cr. The increased threshold will ensure that around 90% of businesses will benefit the simpler compliance under the new GST return framework.

Single GST Return

Types of New GST Returns

Single GST return is introduced with the concept of outward annexure (Form GST ANX-1) and inward annexure (Form GST ANX-II). In outward annexure, the businesses are required to admit the liability by furnishing the outward supplies and inward supplies attracting reverse charge. In-turn, these details will be auto-populated into your main return.

On the other hand, inward annexure will capture the details of purchases for claiming the input tax credit. This annexure will be auto-populated based on the invoices uploaded by your supplier. Like Form GST Anx-1, these details too will be auto-populated into main GST return.

The new GST return framework will significantly reduce the efforts and time required for filing returns as most of the details required are auto-populated into the main returns.

Different Types of New GST Returns

Types of New GST Returns

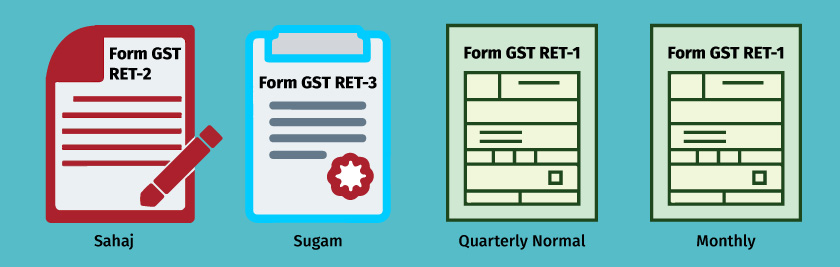
Based on the size the businesses, the type of supplies, customers you deal and the geography, the GST council has designed different type of GST Returns. Sahaj, Sugam and quarterly normal returns are the quarterly return available for small taxpayers. Monthly return (Form GST RET-1) for larger taxpayers.
The returns are so simple that it requires only fewer details basis the business profile and the compliance requirements in relation to ITC are very minimum. It is expected that the cost of compliance will be less.

Profile Based Returns Format

Profile Based Returns Format

Instead of having a common GST return format for all, the council has designed different type of GST returns considering the diversity of business operations. This comes with the option to personalize the return format based on the supplies you make.

As a result, only the relevant information will be shown based on the business profile. For example, a small manufacturer or trader, buying and selling locally may need to file a return consisting of only fewer information.

Continuous Upload of Invoice

continuous uploading of invoices

The new GST return is provisioned for continuous uploading of invoices by the supplier anytime during the month. At the end of the filing period, these invoices will be auto-populated in the return.

By just uploading the Invoices, most of your work-related return filing is done and at the end of the return period, it becomes so simple that you can validate with your tax expert and file the return.

Viewing facility of Invoices     

Viewing facility of Invoices

Based on the invoices uploaded by your supplier, the real-time viewing facility of invoices is made available to the buyer. This achieved by auto-populating the details of the invoices uploaded by the supplier into the inward supplies’ annexure known as Form GST ANX-II. This also comes with an option for looking of invoice.

This will help you to verify and lock the invoice to confirm the eligible ITC. Locking of invoice will ensure that invoices uploaded by your supplier is correct and the invoice will be locked for further modification by the supplier. Thus, the risk of ITC loss in a certain business situation is mitigated.

Amendment of Returns and invoice

The concept of revised returns to be introduced and you will be allowed to revise return for any tax period. Returns will be revised either by filing amendment returns or reporting of missing invoice.  Provision to revise the current returns (GSTR-1 and GSTR-3B) is not available.

Also, amendment (editing) of invoice by the supplier is provisioned in the new GST return framework. The supplier can edit only if the invoice has not been locked by the recipient. If it is already locked, unless it is reset/unlocked by the recipient, the details cannot be edited by the supplier.

No Automatic Reversal of ITC

No automatic reversal of input tax credit at the recipient’s end in the case of default in the payment of tax by the supplier. In such situations, recovery efforts will be first made from the supplier.

ITC on Missing Invoice

Invoices or debit notes which have not been uploaded by the supplier, the recipient is allowed to avail input tax credit (ITC) on a provisional basis in the same month and a window of 2 tax period are allowed to report such missing invoice.

The facility of availing ITC and reporting is allowed for Larger taxpayers (Monthly returns) and small taxpayers filing RET-1 (quarterly normal return). In other words, businesses who have opted Sahaj return and Sugam return will not be allowed avail ITC on the missing invoice.

How to File GST Sahaj Return in Form RET-2

The Sahaj return is a quarterly GST return to be filed by 20th of the subsequent quarter. The businesses whose turnover in the previous financial year is up to 5 Crores and engaged in making outward supplies only to B2C i.e. end consumers or unregistered businesses can opt to file GST Sahaj return. The form to be filed by businesses opting Sahaj is Form RET-2

Though the Sahaj return in form RET-2 filing is on a quarterly basis, the payment of GST needs to be made on monthly basis using the payment declaration form known as Form GST PMT-08. The businesses need to determine the tax liability and Input tax credit on the self-assessed basis and accordingly remit it through Form GST PMT-08

Let’s understand the complete Sahaj return filing Cycle.

How to file Sahaj Return in Form RET-2

The details of outward supplies in GST Sahaj form are required only at a summary level. This is because, GST Sahaj is applicable only if you are making B2C supplies and your customer (the buyer) will not be in a position to claim ITC on the supplies made by you.

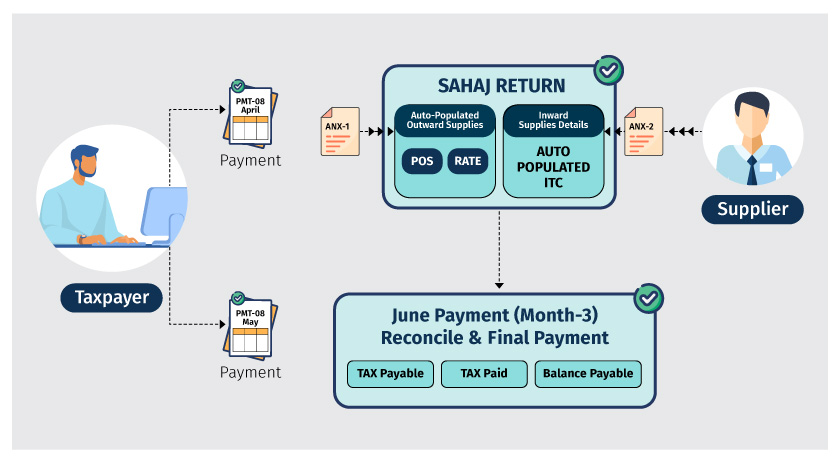
The GST Sahaj return filing cycle through Form RET-02 is explained with an illustration.

filing sahaj returns ret-2

We have considered the April-June, 2019 to explain the GST Sahaj return filing cycle. In the above illustration:

  • The taxpayer makes the self-assessed payment for the month of April, 2019 and May, 2019 using Payment Declaration Form GST PMT-08
  • On completion of the quarter April to June, 2019, GST Sahaj return needs to be filed by 20th of July 2019 with the payment of Tax
  •  The taxpayer needs to furnish the consolidated outward supplies details at rate-wise (5%, 12% etc.) and place of supply-wise in Form GST ANX-1. This, in turn, gets auto-populated into the Sahaj return Form GST RET-2
  • Input Tax credit details will be auto populated in Sahaj return form RET-2
  • As illustrated, as and when the invoices are uploaded by the supplier, details of ITC will be auto-captured in inward supplies annexure ‘ANX-02’ and which in turn gets auto-populated in GST Sahaj return form.
  • Remember, Sahaj returns forms will not have a concept of claiming and reporting ITC on missing invoices which supplier has not uploaded. You can claim the ITC only to the extent of invoice uploaded by the supplier
  • Once the required details are furnished in GST Sahaj return, the next step is to make payment
  • The tax payment here includes:
    • Tax payable for supplies made during 3rd month of the quarter
    • Adjustment due to the difference in tax paid on the self-assessed basis in the first and second month versus the outward supplies’ details declared in the Sahaj return.
    • Adjustment due to ITC claimed on self-assessed basis versus the auto-populated ITC available in inward supplies annexure.
  • Once the tax payment is done, you can submit and file the GST Sahaj returns.

Conclusion

For businesses, the Sahaj return filing cycle is very simple. All you have to do is the self-assessed monthly payment and mention the consolidated details of outward supplies in annexure -1. The rest of the details are auto-populated in Sahaj return. The businesses can leverage on simplification only when they carefully assess their businesses profile and choose the one which is suitable.

37th GST Council Meeting Updates

37th-GST-Council-Meeting-updates_Blog-Banner

The GST Council, headed by Union Finance Minister Nirmala Sitharaman and comprising representatives of all States and Union Territories (UTs), had its 37th meeting in Goa in the backdrop of economic growth hitting a six-year low of 5% for the first quarter of the current fiscal. This GST Council Meeting was extremely crucial as various industries were looking forward to some major decisions to be taken in terms of tax slabs.

There have been demands pouring in from various sectors — from biscuits to automobiles and FMCG to hotels — to reduce tax rates in the wake of economic slowdown.

Here are the key decisions during the 37th GST Council Meeting held in Panaji, Goa which are said to be effective from October 1, 2019.

GST Rates Revisions

  • GST Council recommends lower 12% cess on 1,500 cc diesel, 1,200 cc petrol vehicles with capacity to carry up to 13 people.
  • GST rate on caffeinated beverages raised from 18% to 28% with 12% compensation cess.
  • Uniform GST rate of 12% to be levied on polypropylene bags and sacks used for packing of goods
  • GST exempted on specified defence goods not manufactured in India
  • Rate levied on cut and polished semi-precious stones has been dropped from 3% to 0.25%.
  • Jewellery exports to now attract zero GST.
  • GST on fishmeal used by fishermen being exempted from July 2017 to September 30 this year. There was lack of clarity on their GST coverage and no tax was collected so that has been resolved.
  • GST rate hiked on railway wagon, coaches from 5% to 12%.
  • For Transaction value per unit per day of ₹1000 or less, will attract nil GST. For ₹1001 upto ₹7500, now the tax rate will be 12%. Anything above ₹7501 will attract 18%. It was 28% till now.
  • To reduce the rate of GST on hotel accommodation service as below:
Transaction Value per Unit (Rs) per day GST
Rs 1000 and less Nil
Rs 1001 to Rs 7500 12%
Rs 7501 and more 18%
  • To exempt services provided by an intermediary to a supplier of goods or recipient of goods when both the supplier and recipient are located outside the taxable territory.

New Returns

  • Waiver off the requirement of filing FORM GSTR-9A for Composition Taxpayers for FY 2017-18 and FY 2018-19
  • Filing of FORM GSTR-9 for those taxpayers who (are required to file the said return but) have aggregate turnover up to Rs. 2 crores made optional for FY 2017-18 and FY 2018-19
  • A committee to examine simplification of Forms for Annual Return and reconciliation statement
  • New return system now to be introduced from April 2020 (earlier proposed from October 2019)
  • The imposition of restrictions on availing of input tax credit by the recipients in cases where details of outward supplies are not furnished by the suppliers.

Other Crucial Updates

  • Group insurance schemes for paramilitary forces under the Home Affairs ministry to be exempted from GST.
  • Aerated drink manufacturers shall not be under the composition scheme anymore.
  • Rate reduction on hotel accommodation services.
  • Job work services related to diamonds reduced from 5% to 1.5%. For machine job works in engineering industry, GST down from 18 to 12. But bus body building works still taxed at 18%.
  • Restriction on refund of compensation cess on tobacco products (in case of inverted duty structure)
  • Reasonable restrictions on passing of credit by risky taxpayers including risky new taxpayers
  • Link Aadhar with registration of taxpayers under GST and examine the possibility of making Aadhar mandatory for claiming refunds
  • Integrated refund system with disbursal by single authority to be introduced from 24th September 2019